Bangalore Real Estate Affordability
Featured Image of Bangalore Real Estate Affordability


Bangalore real estate affordability depends on the home price, your income, down payment and loan cost. Knight Frank’s H1 2026 index puts the city’s home loan EMI-to-income ratio at 35%, up from 34% in 2025. This means affordability has weakened slightly. The index uses a typical city home and household income; it does not show what every family can afford.

For a practical example, a ₹1 crore home with a ₹25 lakh down payment leaves a ₹75 lakh loan. At an assumed 8.5% interest rate over 20 years, the EMI is about ₹65,087 a month. Taxes, fees, interiors and upkeep add to the cost. The same budget check applies to premium homes such as Brigade Granada in East Bangalore’s Whitefield–Hoskote corridor.
Is Bangalore Real Estate Affordable in 2026?


Bangalore sits between India’s lower-cost and higher-cost housing markets in the latest index. Its 35% ratio is below Hyderabad’s 41% and Mumbai Metropolitan Region’s 69%. It is above Pune’s 28% and Chennai’s 29%. These figures compare cities using the same research framework.

For an individual buyer, the city average is only a starting point. A family with two steady incomes may have more room for an EMI. A single earner with rent, school fees and an existing loan may find the same home costly.

The useful test is what remains after paying for the home. There should still be room for daily needs, savings and sudden expenses.

Bangalore Home Prices and Affordability


Knight Frank reported an average residential price of ₹9,354 per sq. ft. in H1 2026, a 9% annual rise. This is a market measure, not a quote for every flat. Prices vary by location, building age, size and project type.

Compare homes within the same area before deciding what is affordable. Check the area basis used in the quote. A rate based on carpet area cannot be compared directly with one based on super built-up area.

The full price matters more than the lowest advertised rate. Ask what is included in the cost sheet. Parking, floor charges and other items can change the final amount.

How Much Income Is Needed to Buy a Home in Bangalore?


One way to plan is to keep the home loan EMI near 35% of monthly take-home pay. This is an illustrative budget choice, not a bank rule. Buyers with other debts or high household costs may need a lower limit.

The examples below assume a 25% down payment, an 8.5% loan rate and a 20-year term. They exclude purchase charges and monthly upkeep.

Home price Down payment Loan amount Approximate EMI Take-home pay at a 35% EMI share
₹1 crore ₹25 lakh ₹75 lakh ₹65,087 ₹1.86 lakh a month
₹1.50 crore ₹37.50 lakh ₹1.125 crore ₹97,630 ₹2.79 lakh a month
₹2 crore ₹50 lakh ₹1.50 crore ₹1,30,173 ₹3.72 lakh a month

Actual loan rates and funding depend on the lender’s assessment. A larger down payment lowers the EMI, but it should not use up all your savings.

Upfront Costs Beyond the Down Payment


A home purchase needs more cash than the down payment alone. Allow for stamp duty, registration, legal checks and lender fees. For an under-construction home, applicable taxes and deposits may also form part of the bill.

Interiors are another cost. A flat may need wardrobes, kitchen work, lights and appliances before you move in. Get estimates rather than assuming that the sale price covers a ready home.

Keep an emergency fund separate from the purchase budget. This gives you some room if income stops or a large expense comes up.

Home Loan Rates Can Change Affordability


A small rate rise can have a clear effect on a large loan. On a ₹75 lakh loan over 20 years, the EMI is about ₹65,087 at 8.5%. At 9.5%, it rises to about ₹69,910.

That is an extra ₹4,823 a month. A floating-rate lender may change the EMI, loan term or both, subject to the loan terms. Test your budget at a higher rate before choosing the maximum loan offered.

A longer term lowers the monthly payment. It also means paying interest for more years. Compare the total repayment, not just the first EMI.

Location and Bangalore Apartment Affordability


A lower-priced home farther from work can reduce the purchase cost. It may also increase travel costs and time. Check both before choosing the area.

For example, an extra ₹5,000 a month on travel adds up to ₹60,000 a year. That can reduce the benefit of a slightly lower EMI. School transport and frequent cab trips can add more.

For homes in the Whitefield–Hoskote belt, test the route from the project entrance. A broad Whitefield address does not mean every project has the same access to offices, shops or metro stations.

Brigade Granada and Bangalore Real Estate Affordability


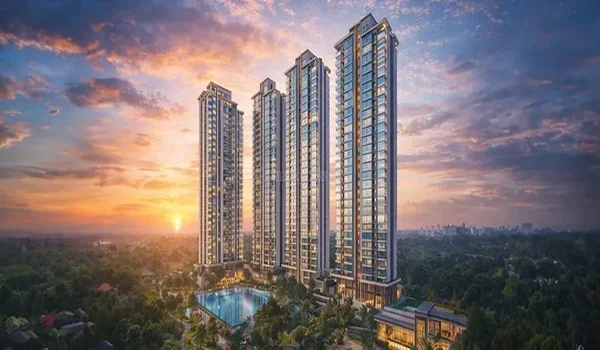
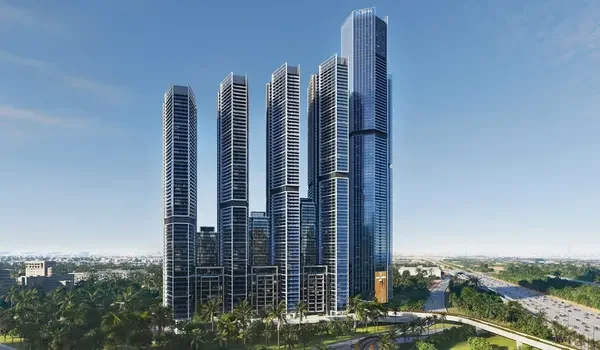
Brigade Granada is a proposed mixed-use township in the Whitefield–Hoskote corridor. The working project details describe 40+ acres, 14 residential towers, about 2,000 apartments and 1, 2, 3 and 4 BHK homes. Its indicative starting price is about ₹1 crore, with final prices and plans to be checked against the current project documents.
At that entry budget, the ₹1 crore loan example gives a useful starting point. A buyer would need more than the ₹25 lakh down payment once other charges are included. Larger homes will need a higher cash contribution and EMI. The township’s planned facilities should also be weighed against future upkeep costs and the wait for handover.
Buying an Under-Construction Home: Rent and EMI


An under-construction purchase may involve rent and loan payments at the same time. This overlap can make a home less affordable than the final EMI suggests.
At ₹30,000 a month, three years of rent totals ₹10.80 lakh, before rent rises. Loan payments may start during that period, based on the payment plan and disbursement.

Ask the lender to explain pre-EMI and full EMI options. Include the overlap in your budget instead of counting only the cost after moving in.

Ways to Improve Home-Buying Affordability


Choosing a smaller home can lower the loan and upfront cost. Compare layouts carefully; a useful two-bedroom home may suit your needs better than a larger flat with wasted space.

Paying off an existing loan can also free up monthly income. A larger down payment helps, provided enough savings remain for emergencies.

Finally, compare complete cost sheets. A discount has value only when the final cost is fair against similar homes. Check ready resale flats as well as new launches.

FAQs


1. Is Bangalore real estate affordable for a middle-income family?

It depends on the price and household budget. A lower-cost home, two incomes or a larger down payment can help. Existing debt can reduce buying power.

2. Can I buy a Bangalore home on a ₹1 lakh monthly salary?

It may be possible with a lower purchase price or substantial savings. In the example above, a ₹75 lakh loan needs an EMI of about ₹65,087, leaving limited room from ₹1 lakh take-home pay.

3. What is the EMI for a ₹1 crore home?

With a ₹25 lakh down payment, a ₹75 lakh loan at an assumed 8.5% over 20 years costs about ₹65,087 a month.

4. Is rent included in the affordability calculation?

Your personal budget should include rent until handover. It is an added cash cost while buying a home under construction.

5. Is Brigade Granada an affordable housing project?

Its indicative starting price of about ₹1 crore places it in a premium budget. Whether it is affordable depends on the buyer's income, savings and chosen home.

6. What should I check before booking?

Check the final cost sheet, loan terms, payment dates and handover terms. Add upkeep, rent overlap and move-in costs to the budget.

Brigade Granada Blog


Enquiry
Enquire Now