Brigade Granada Retirement Wealth Guide 2026
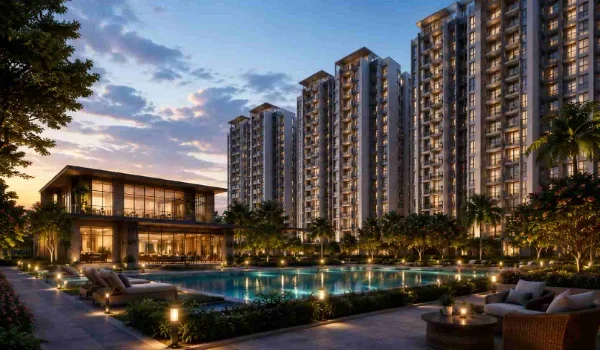
Featured Image of Brigade Granada Retirement Wealth Guide 2026


A Brigade Granada flat builds retirement wealth in three ways: price growth, rental income and a flexible exit. You gain from price growth while the towers rise between 2026 and January 2031. After possession, the flat can earn monthly rent from Whitefield's large pool of IT tenants. You also keep the choice to sell, rent it out or move in yourself later. The 10:10:80 payment plan spreads most of the cost across your remaining salary years. This guide shows you how to time the purchase, pick the unit and plan your exit.
What Brigade Granada Offers a Retirement Investor


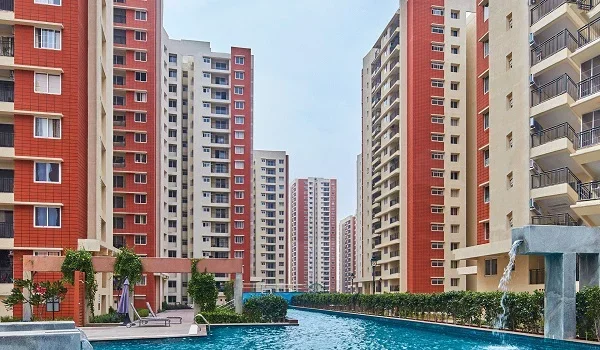
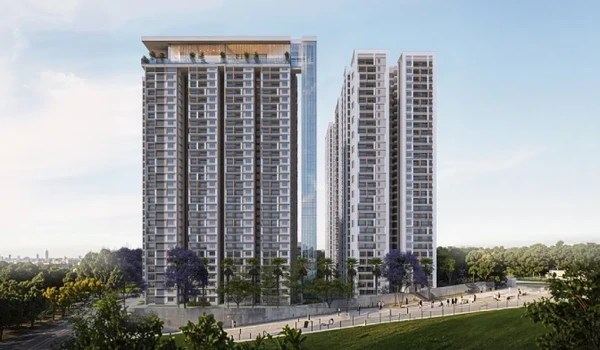
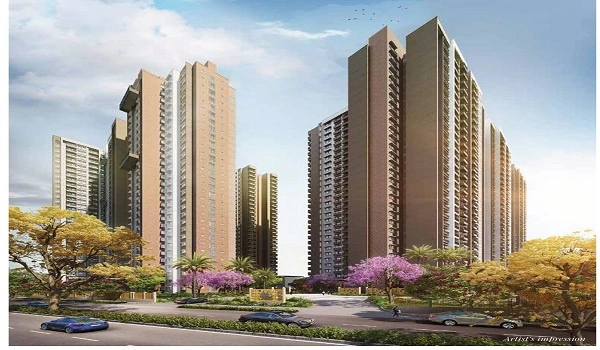
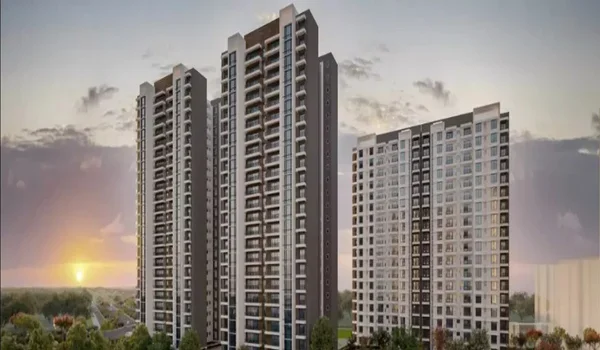
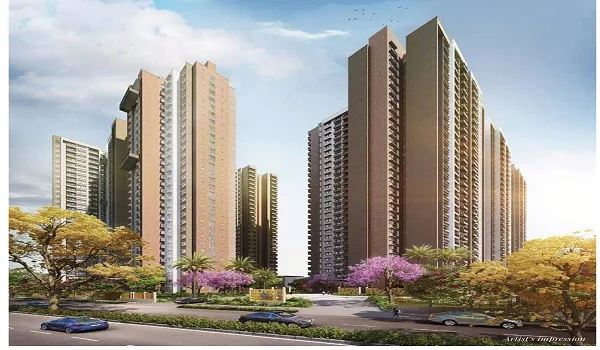
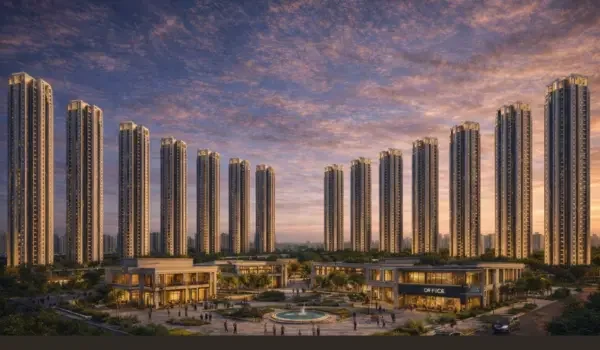
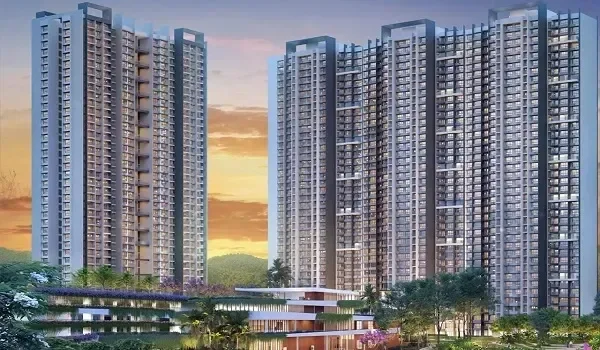
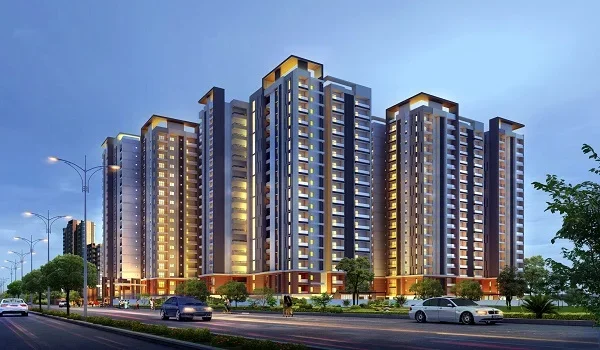
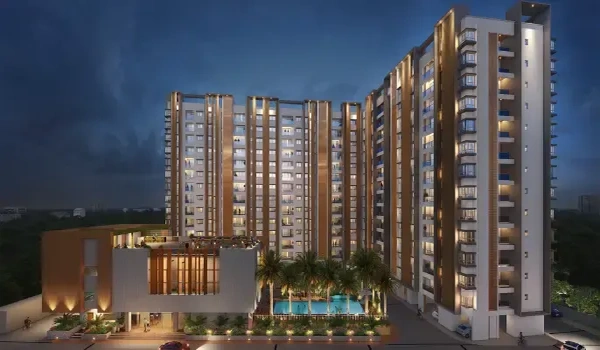
Brigade Group is building Brigade Granada as a 40-acre mixed-use township in East Bangalore. It sits at Seegahalli, off Whitefield Kadugodi Road, about 2 km from Kadugodi Metro. The plan holds 14 towers with about 2,000 homes, and 80% of the land stays green. Prices start from ₹1 crore, and units range from 600 sq ft to 2,800 sq ft.

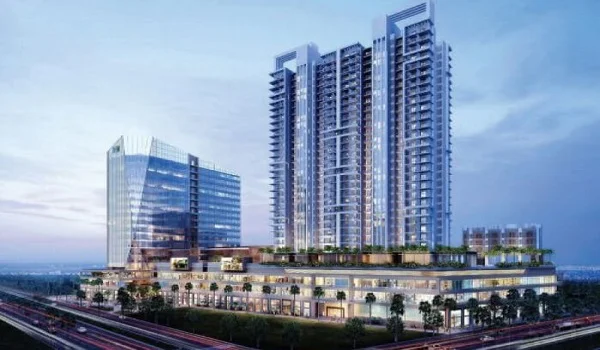
For a retirement buyer, the mixed-use plan matters more than the clubhouse list. The township plans a hospital, a school, a retail hub, a hotel and an office tower. A hospital within walking distance counts for a lot once you cross sixty. The 35-floor office tower and 400-key hotel also bring tenants who want short commutes.

Factor Detail Why It Matters for Your Retirement
Location Seegahalli, off Whitefield Kadugodi Road ITPL and Whitefield offices keep rental demand steady
Metro access Kadugodi Metro is about 2 km away You can travel across the city without driving in later years
Healthcare Hospital planned inside the township You reach medical care faster as you age
Unit range 1 to 4 BHK, 600 to 2,800 sq ft You can match the size to an income goal or a downsizing plan
Payment plan 10:10:80, with 8 construction milestones Your outflow spreads across your earning years
Possession 31 January 2031 Rental income can start only after this date
RERA Approval expected in the first week of October 2026 Check the live number before you pay beyond the EOI

Time the Purchase Around Your Retirement Age


Your age at booking decides how comfortably you can carry the payments. Most banks want a salaried borrower to close the home loan by about 60 to 65. Each lender sets its own limit, so check with two or three banks early. A buyer at 42 and a buyer at 55 need very different plans for the same flat.

Your Age Today Your Age at Possession (2031) How to Plan the Purchase
40 to 45 45 to 50 Take a longer loan and let rent cover the EMI for years
46 to 52 51 to 57 Pick a shorter tenure and put a larger down payment from savings
53 and above 58 and above Pay mostly from savings or a property sale, and keep borrowing low

Your money earns no rent for a little over four years, until possession in January 2031. Fit the construction milestones into your monthly budget before you sign anything. They should never pull money out of your PPF, NPS or emergency fund. A buyer who stops retirement savings to fund one flat often ends up asset rich but cash poor.

Pick the Unit That Fits Your Retirement Goal


The right configuration depends on what you want from the flat after 2031. Some buyers want monthly rent, while others want a smaller home to live in. A third group wants a large asset to pass on to their children.

Configuration Size (sq ft) Best Retirement Use
1 BHK 600 to 700 Lowest entry price, rents quickly to single IT professionals
2 BHK Regular 1,000 to 1,100 An easy home for a retired couple to run and clean
2 BHK Large 1,200 to 1,300 A couple's home with a spare room for visiting children
3 BHK + 2T and 3 BHK + 3T 1,400 to 1,650 Strong family rental demand from the Whitefield office belt
3 BHK Large and 3 BHK Study 1,800 to 2,200 Live in now, then rent out or sell when you downsize
4 BHK 2,500 to 2,800 Joint family living, with higher upkeep and maintenance bills

Smaller units usually earn a better rent for their price, so they suit an income goal. If you plan to live here after retiring, a 2 BHK keeps upkeep under control. Brigade bills maintenance on super built-up area, so a bigger flat costs more every month.

A Worked Example With Real Numbers


Take an illustrative unit priced at ₹1.5 crore to see how the money moves. These figures show the method only, so ask Brigade for your own cost sheet.

Payment Stage Share Amount on ₹1.5 Crore
Booking 10% ₹15 lakh
Allotment, after the sale agreement 10% ₹15 lakh
Construction, across 8 milestones 80% ₹1.2 crore, about ₹15 lakh per milestone

GST at 5% on an under-construction home adds about ₹7.5 lakh to this bill. You also pay Karnataka stamp duty and the 2% registration fee when you register the flat.

Market data from 2026 puts Whitefield's gross rental yield at roughly 3% to 4% a year. At 3%, this flat would earn about ₹4.5 lakh a year, or roughly ₹37,500 a month. Rent alone will not make you rich, but it can cover maintenance and property tax. It can also pay some of your household bills after you stop working.

Price growth usually does the heavy lifting for wealth in this corridor. If the flat gains 5% a year, ₹1.5 crore grows to about ₹2.44 crore in ten years. Treat this as a scenario, not a promise, because nobody can fix future prices.

Tax Rules That Shape Your Final Return


Tax can quietly eat a large slice of your gain, so plan for it from day one.

  • Home loan interest: The old tax regime lets you claim up to ₹2 lakh a year on home loan interest. You claim pre-possession interest in five equal parts after you receive the keys.
  • Rental income: You pay tax on rent as income from house property, after a flat 30% standard deduction.
  • Selling the flat: If you hold the flat for more than 24 months, your profit counts as long-term capital gain. For property bought after 23 July 2024, this gain attracts 12.5% tax without indexation.
  • Section 54 relief: You can save this tax by putting the gain into another home within the set time limits. The exemption under this section carries a ceiling of ₹10 crore.

Speak with a chartered accountant before you sell, since timing changes the final tax bill.

Risks You Should Weigh Before You Pay


Every pre-launch purchase carries risk, and a retirement buyer has less time to recover.

  • Brigade still awaited RERA approval in early October 2026, so pay nothing beyond the EOI yet. Wait until the registration number shows live on the Karnataka RERA website.
  • Possession sits more than four years away, so any delay pushes your first rent cheque further out.
  • Keep your full retirement corpus out of one flat, because you cannot sell part of it. A ₹5 lakh hospital bill needs cash, not a property listing.
  • Brigade Granada is a regular township, not a senior living project with nursing staff. Plan assisted care or home nursing separately if you expect to need it.
  • Large townships open in phases, so the hospital and hotel may follow the homes. Ask the sales team for a written timeline for each of these facilities.
Who Should Consider Brigade Granada for Retirement


This project suits you if you are 40 to 52 and earn a steady salary. It works best when you want an asset that matures close to your retirement. It also fits an NRI who plans to return and wants a home near metro and hospital. Buyers with a strong emergency fund and some equity or debt investments gain the most here.

It suits you less if you need monthly income now, or if it absorbs most savings. In that case, a ready-to-move flat or senior citizen schemes may serve you better.

FAQs


1. Is Brigade Granada a good retirement investment?

It can work well if you buy in your forties or early fifties and hold for ten years. Most of your return comes from price growth, with rent adding income after January 2031.

2. Which unit at Brigade Granada suits a retired couple?

A 2 BHK Regular of 1,000 to 1,100 sq ft is the easiest to run and maintain. Choose the 2 BHK Large if your children visit often and need their own room.

3. When will a Brigade Granada flat start earning rent?

Rent can start only after possession on 31 January 2031 and your interior work. Plan for no rental income during the four-plus years of construction.

4. Can I get a home loan for Brigade Granada at age 50?

Yes, most banks will lend, but they usually want the loan closed by 60 to 65. That means a shorter tenure, so expect a higher EMI or pay more upfront.

5. What payment plan does Brigade Granada offer?

The plan is 10:10:80, linked to real progress on site. You pay 10% at booking and another 10% after signing the sale agreement. The remaining 80% follows eight construction milestones until the towers reach completion.

6. Is Brigade Granada a senior living project?

No. Brigade Granada is a mixed-use township for buyers of every age. A planned hospital and nearby metro help older residents, but the project offers no nursing care. Ask the site team for the latest cost sheet and floor plans for your shortlisted unit. Then test the numbers with your financial planner before you hand over the EOI cheque.

Brigade Granada Blog


Enquiry
Enquire Now